
Categories
Home Buying TipsPublished September 24, 2026
Can a Seller Pay to Lower My Mortgage Rate on a Katy, TX Home?
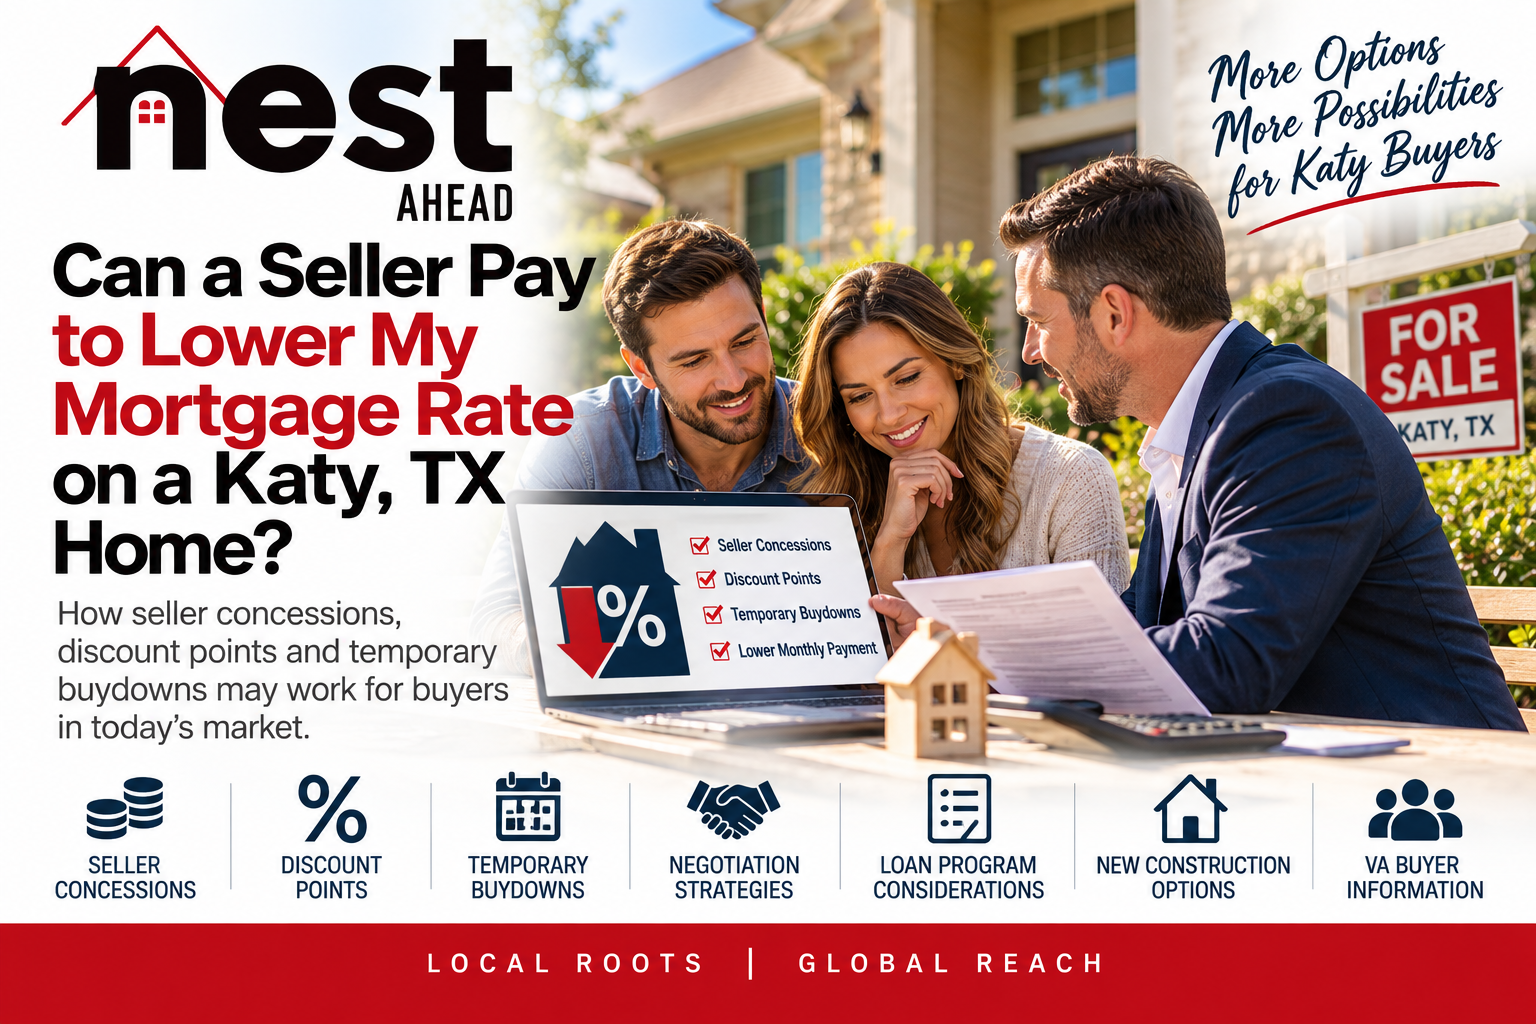
If mortgage rates are making the monthly payment on a Katy, TX home uncomfortable, can the seller help pay to lower your rate?
Potentially, yes.
Depending on the loan program, lender requirements, contract terms and what the seller is willing to negotiate, seller contributions may sometimes be used toward eligible buyer financing costs.
That could potentially include costs associated with discount points or an eligible temporary mortgage-rate buydown.
But there is an important distinction:
A seller does not simply choose a lower mortgage rate for the buyer.
The financing has to be structured through the buyer's lender, comply with the applicable loan program and fit within any limits on seller contributions.
That's why I want the lender involved before we decide how to structure the negotiation.
What Are Discount Points?
Discount points are fees paid upfront in exchange for a lower mortgage interest rate.
Freddie Mac explains that one discount point equals 1% of the loan amount. However, there is no universal rule saying that one point will reduce every borrower's mortgage rate by a particular amount.
Freddie Mac: What You Need to Know About Discount Points
The actual cost and rate reduction are determined through the lender.
Depending on the transaction and financing, a negotiated seller contribution may potentially be used toward eligible discount points.
For some buyers, that could create more useful monthly-payment relief than applying the same amount entirely toward a purchase-price reduction.
But that needs to be calculated, not assumed.
What Is a Temporary Mortgage-Rate Buydown?
A temporary buydown works differently.
Instead of permanently changing the note rate, funds are used to temporarily subsidize a portion of the borrower's principal-and-interest payment during the early years of the mortgage.
For example, you may hear terms such as a 2-1 buydown.
Under that type of structure, the payment may initially be calculated using a rate two percentage points below the note rate, then one percentage point below the note rate the following year, before reaching the full note-rate payment.
Not every mortgage qualifies for every buydown structure, and lender and loan-program requirements apply.
Freddie Mac: Temporary Subsidy Buydown Plans
Does a Temporary Buydown Mean My Mortgage Rate Permanently Changed?
No.
This is an important distinction.
A temporary buydown subsidizes the borrower's payment during the temporary buydown period.
The underlying note rate still matters.
That means a buyer considering a temporary buydown should understand what the payment becomes after the subsidy ends.
I would not want a buyer looking only at the first-year payment and ignoring the eventual full payment.
What Is a Permanent Mortgage-Rate Buydown?
A permanent buydown generally involves paying discount points upfront to obtain a lower interest rate for the mortgage.
That differs from a temporary buydown because the negotiated lower rate is not simply an introductory payment subsidy.
But whether purchasing points makes financial sense depends on the cost, the actual rate reduction, how long the buyer expects to keep the mortgage and other factors.
That's a calculation the buyer should review with the lender.
Is a Seller Required to Pay for a Buydown?
No.
A seller contribution is a negotiated contract term.
The seller may accept it, reject it or counter it.
Whether asking makes sense depends heavily on the property.
A home that has been sitting on the market with limited activity may present a different negotiating opportunity from a newly listed home receiving multiple offers.
That's why I don't believe buyers should approach every Katy property with the exact same negotiation strategy.
Could $10,000 Toward My Rate Be Better Than $10,000 Off the House?
Possibly.
But there isn't one correct answer for every buyer.
Imagine that a seller is willing to provide approximately $10,000 of economic value in the transaction.
Depending on the financing and contract, that value might potentially be applied toward:
- A lower purchase price
- Eligible closing costs
- Discount points
- An eligible temporary buydown
- Repairs or other negotiated items
The best use depends on what the buyer is trying to accomplish.
A buyer who needs to preserve cash may have different priorities from a buyer primarily concerned with reducing the monthly payment.
The question isn't simply, "How much can we get from the seller?"
The better question is, "Where does the negotiation create the most usable value for this buyer?"
Why Should the Lender Be Involved Before We Make the Offer?
Because the lender can tell us what the buyer can actually use.
Before structuring a financing-related seller contribution, I want the buyer discussing questions such as:
- How much would discount points cost?
- How much would those points reduce my rate?
- What would the monthly payment become?
- Would a temporary buydown be available?
- What would my payment be during each year of the buydown?
- What would my full payment be after the temporary subsidy ends?
- What seller-contribution limits apply to my loan?
- Could I use the entire requested contribution?
- Would closing-cost assistance be more useful instead?
I am a REALTOR®, not a mortgage lender.
My role is to help evaluate the real estate opportunity and negotiate the contract.
The lender determines how the financing works.
Those two sides need to communicate.
What About Builder Mortgage-Rate Incentives?
This is especially relevant for buyers considering new construction in Katy, TX.
Builders sometimes advertise reduced mortgage rates, closing-cost assistance or other incentives, frequently in connection with an affiliated or preferred lender.
Those offers can be valuable.
But buyers should compare the entire transaction rather than evaluating only the advertised rate.
That includes:
- Purchase price
- Interest rate
- APR
- Points
- Lender fees
- Closing costs
- Cash required at closing
- Property taxes
- MUD taxes or other assessments where applicable
- HOA assessments
- Insurance
- Builder upgrades and incentives
A promotional mortgage rate can be important, but it is only one part of the financial picture.
What About VA Buyers?
VA financing has its own rules regarding allowable seller concessions, closing costs and financing.
If you're using VA financing, I want your VA lender involved before we structure the offer so we understand exactly what is permitted and useful in your particular transaction.
On the real estate side, I am a VA Certified REALTOR®, Military Relocation Professional (MRP) and approved Veterans Land Board participating REALTOR®.
You can also read my guide:
How Do I Find a Real Estate Agent Experienced With VA Buyers in Katy, TX?
Should I Ask the Seller to Lower My Rate?
Maybe.
But I wouldn't decide that until we know three things:
- What the seller may realistically be willing to negotiate.
- What your lender says you can use.
- Which option produces the most useful financial result for you.
Sometimes that could be a financing-related contribution.
Sometimes closing-cost assistance may be more valuable.
Sometimes the purchase price matters more.
And sometimes the seller simply isn't willing to make the concession.
Good negotiation isn't about asking for the biggest headline number. It's about understanding where the available dollars create the greatest value.
Buying a Home in Katy, TX?
If you're considering a home in Katy, TX and wondering what might realistically be negotiable, we can look at the individual property, comparable sales, competing listings, days on market and current market conditions.
Your lender can then run the financing scenarios.
Together, those numbers can help you make a much more informed decision about whether to negotiate price, closing costs, financing expenses or something else.
Call or text me at 281-549-8099 or learn more at Jonathan.NestAhead.com.
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX and Greater Houston
281-549-8099
Jonathan.NestAhead.com
Local Roots | Global Reach
This article is provided for general real estate education and is not mortgage, lending, legal, tax or financial advice. I am a REALTOR®, not a mortgage lender. Loan programs, seller-contribution limits, discount points, temporary buydowns, qualification requirements and financing terms vary. Buyers should review their individual financing with an appropriately qualified mortgage professional.
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way