
Categories
Katy, TX Home Buying, Katy TX Real EstatePublished September 7, 2026
How Much Money Do You Really Need to Buy a House in Katy, TX?
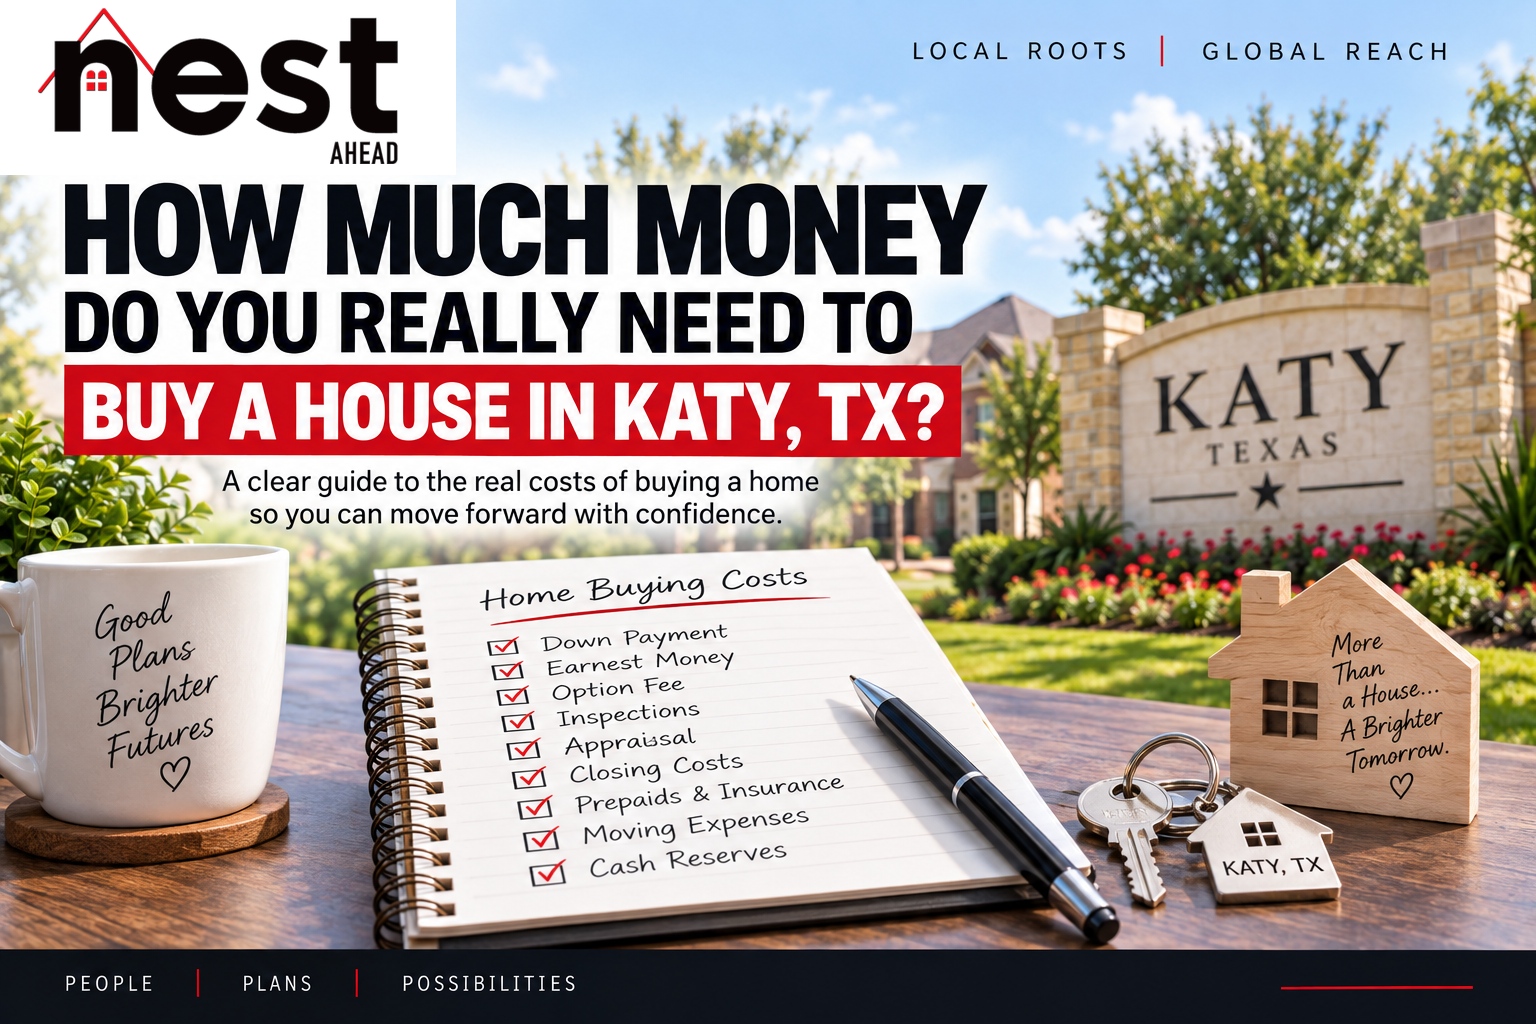
Buying a $400,000 home in Katy, TX does not necessarily mean you need $80,000 sitting in the bank for a 20% down payment.
But it also does not mean the down payment is the only money you will need.
One of the most common questions buyers ask is, “How much money do I actually need to buy a house?”
The answer depends on your financing, the property, the contract, your lender’s requirements and your individual circumstances. Your lender should determine the loan-specific numbers, but as your REALTOR®, I want you to understand the different expenses that can arise during a purchase so there are fewer surprises between the day we start looking at homes and closing day.
Instead of focusing on one percentage, it is more useful to think about your home purchase in several different “buckets” of money.
1. Your down payment
The first bucket is the amount you put toward the purchase price of the home.
A common misconception is that every buyer must put 20% down. That is not true. Some conventional loan programs allow qualified borrowers to purchase with as little as 3% down, FHA-insured financing can allow a minimum required investment as low as 3.5% for qualifying borrowers, and eligible VA buyers may be able to purchase with no down payment in many circumstances. Certain USDA programs can also provide no-down-payment financing for eligible borrowers and eligible properties.
Those are not recommendations about which loan you should use. I am not a lender, and loan eligibility, underwriting, credit requirements, income limits, property eligibility, mortgage insurance, funding fees and other terms can vary. A qualified mortgage professional should evaluate your individual situation and explain the options available to you.
For official program information, buyers can review resources from HUD/FHA, U.S. Department of Veterans Affairs, Fannie Mae HomeReady and Freddie Mac Home Possible.
2. Earnest money
Earnest money is another amount buyers should be prepared for when making an offer on a Texas home.
In a typical residential contract, earnest money is delivered after the contract is executed in accordance with the contract terms. It is generally credited toward the buyer’s transaction at closing if the transaction proceeds to closing.
There is not one universal earnest-money amount that applies to every Katy, TX purchase. The amount can be negotiated and may depend on the price of the home, market conditions, the strength of the offer and other terms of the transaction.
When we prepare an offer, I can explain the real estate and negotiation considerations surrounding earnest money. Questions about how the contract applies to a specific legal situation should be directed to an attorney.
3. The option fee
Texas buyers may also negotiate an option period as part of the purchase contract.
The option fee and length of the option period are negotiable terms. During the option period, buyers commonly perform inspections and other due diligence.
Just like earnest money, there is no single option fee that is automatically appropriate for every property or every offer.
When we are writing an offer, we will evaluate the situation and discuss how the amount and length of the option period may affect the overall strength of the offer.
4. Home inspection and other due-diligence expenses
A professional home inspection is typically paid by the buyer directly and is generally an out-of-pocket expense that occurs before closing.
Depending on the property, a buyer may also choose or need additional evaluations. These could involve areas such as the foundation, roof, HVAC system, plumbing, electrical systems, pool, septic system, well, termites or other property-specific concerns.
Not every home needs every type of inspection. The point is to make room in your budget for due diligence rather than assuming every dollar you have available can go toward the down payment.
5. The appraisal
If you are financing the purchase, your lender may require an appraisal.
The lender controls the appraisal process and can tell you how the appraisal fee will be handled and when it must be paid.
An appraisal and a home inspection serve different purposes. The inspection is primarily for the buyer’s evaluation of the property, while the appraisal is generally ordered for the lender’s valuation and collateral requirements.
6. Closing costs
Closing costs are separate from the down payment.
Depending on the transaction and loan, these can include lender charges, title-related charges, settlement expenses, recording fees and other costs associated with obtaining the mortgage and completing the purchase.
Your lender should provide the loan-specific estimates and disclosures that explain your anticipated financing costs. The title company can explain title and settlement charges associated with the closing.
Do not rely on a generic online percentage to determine exactly what your closing costs will be. Your financing, purchase price, property, insurance, tax situation and contract terms can all affect the final amount.
7. Prepaid expenses and escrow funding
This is an area buyers sometimes overlook.
Depending on your loan and closing date, you may need funds for prepaid homeowners insurance, prepaid interest and amounts collected to establish an escrow account for future taxes and insurance.
In the Katy area, property taxes can be especially important to understand because tax rates can vary by property and may include county, school district, municipal utility district and other taxing entities.
Before choosing a home based only on the sales price, look at the property’s complete tax picture. You can learn more in my Katy, TX Property Tax Guide and my article about MUD taxes in Katy, TX.
8. Homeowners insurance
Homeowners insurance is another important part of the purchase budget.
Your lender may require evidence of acceptable coverage before closing, but buyers should also evaluate the cost of insurance as part of the ongoing monthly affordability of a home.
Insurance premiums can vary substantially from property to property. Roof age, claims history, construction characteristics, coverage selections, deductibles and other factors may affect pricing.
Getting an insurance quote early in the option period can help reduce the chance of an unpleasant surprise near closing.
9. Moving and immediate homeownership expenses
Your cash planning should not stop at the closing table.
After buying a home, you may immediately encounter expenses for movers, utility deposits, changing locks, window coverings, appliances, furniture, lawn equipment, pest service, security systems or other household needs.
A resale home may also have repairs or improvements you want to make shortly after closing.
That is one reason I do not want buyers to think only in terms of, “What is the maximum amount I can use for my down payment?”
Closing with some financial breathing room can be very different from closing with almost no cash remaining.
10. Cash reserves after closing
The amount a lender approves you to borrow is not the same thing as the amount you personally should feel comfortable spending.
Homeownership comes with expenses that renters may not be accustomed to paying directly. Air-conditioning systems need service. Water heaters fail. Appliances stop working. Property taxes and insurance can change over time.
Your lender and financial adviser can help you evaluate the financial side of maintaining appropriate reserves. From the real estate side, I encourage buyers to think beyond simply getting to closing.
The goal should be sustainable homeownership, not simply qualifying for the highest possible purchase price.
Can the seller help with closing costs?
Sometimes a purchase can be structured so that the seller contributes toward certain buyer closing costs, subject to the contract and the buyer’s loan-program rules.
Whether a seller is willing to do that depends heavily on the market, the individual property and the overall terms of the offer.
A seller contribution is not “free money.” It is one negotiated component of the transaction, and the price and other terms of the offer still matter.
I can help you evaluate the real estate negotiation. Your lender must determine what contributions are permitted under your financing and how they affect your cash-to-close.
What about builder incentives?
New-home builders sometimes advertise incentives toward closing costs, interest-rate programs, upgrades or other buyer expenses, particularly when buyers use an affiliated or preferred lender or title company.
The headline incentive should not be evaluated in isolation.
We need to compare the home price, financing terms, lender charges, available inventory, upgrade costs and contract terms so you understand the overall transaction.
If you are considering new construction in Katy, TX, it is important to involve your REALTOR® before registering with or visiting a builder so your representation can be established from the beginning.
Are down-payment-assistance programs available in Texas?
Potentially. Texas has homebuyer programs that may provide down-payment or closing-cost assistance to eligible buyers.
For example, the Texas Department of Housing and Community Affairs Homebuyer Program provides information about mortgage and down-payment-assistance options, subject to program requirements and availability.
Eligibility can depend on income, loan type, property, homebuyer education and other program-specific requirements. These programs also change over time, so buyers should verify current guidelines with an approved participating lender rather than relying on an old article, social-media post or online calculator.
I can help you identify real estate considerations, but your lender should determine whether you qualify for a particular financing or assistance program.
So how much money should you have before buying?
There is no honest one-number answer that applies to every Katy, TX buyer.
Your total amount may include:
- your down payment;
- earnest money;
- the option fee;
- inspection and due-diligence costs;
- an appraisal fee when applicable;
- lender and closing costs;
- prepaid taxes, insurance or interest;
- initial escrow funding when required;
- moving expenses; and
- money you intentionally keep in reserve after closing.
Some of those amounts may ultimately be credited or handled differently at closing depending on your contract and financing, but you should understand the timing of when money may be needed.
The best first step is not browsing homes
Before we start seriously looking at homes, I would much rather have you know what the entire purchase could look like financially than simply know the maximum price a lender says you can qualify for.
Ask a qualified lender to give you an estimate showing the anticipated down payment, closing costs, prepaid expenses and total estimated cash needed to close at several purchase prices.
Then we can use that information to make smarter real estate decisions.
For example, if a $450,000 approval leaves you uncomfortable after accounting for taxes, insurance and cash reserves, we do not have to shop at $450,000. We can build the home search around a price and monthly obligation that better fits your goals.
Buying a home in Katy, TX?
If you are planning to buy in Katy, TX, I can help you understand the real estate process, evaluate resale and new-construction options, analyze properties and structure an offer once you find the right home.
You can also visit my Katy Home Buyer Class for additional buyer education before you begin.
The earlier we coordinate with your lender, the easier it is to build a home search around realistic numbers instead of discovering late in the process that your expected cash-to-close was incomplete.
Important: Jonathan McNabb is a Texas real estate broker/REALTOR® and is not a mortgage lender, attorney, tax adviser or financial adviser. This article is provided for general real estate education only and is not legal, lending, tax or financial advice. Loan programs, eligibility requirements, interest rates, fees, assistance programs and underwriting guidelines can change and vary by borrower and property. Buyers should consult qualified lending, legal, tax and financial professionals regarding their individual circumstances.
About the Author
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX REALTOR® and longtime Katy resident
Local Roots | Global Reach
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way