
Categories
Home Buying TipsPublished September 21, 2026
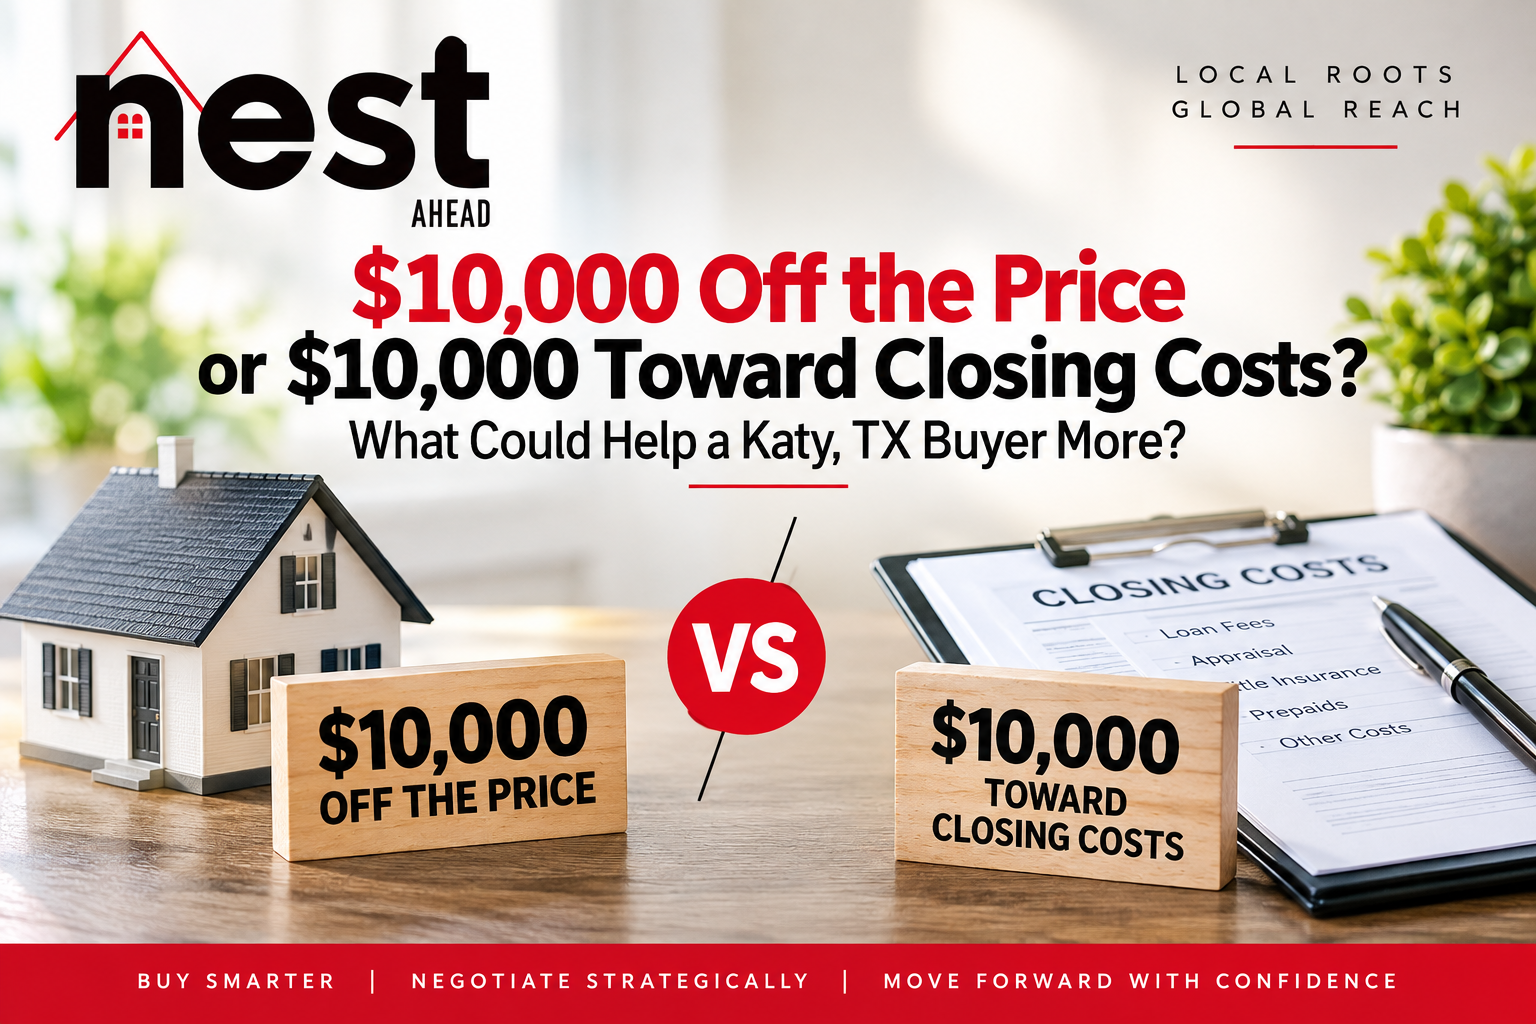
$10,000 Off the Price or $10,000 Toward Closing Costs? What Could Help a Katy, TX Buyer More?
Imagine you are buying a home in Katy, TX and the seller appears willing to negotiate about $10,000 in value.
What should you ask for?
$10,000 off the purchase price?
Or:
$10,000 from the seller toward allowable buyer closing costs?
At first glance, it sounds like the same $10,000.
But from the buyer's perspective, the two options can produce very different results.
A price reduction changes the amount you are paying for the property. An allowable seller contribution may reduce certain costs the buyer otherwise would need to pay in connection with closing, subject to the contract, loan program, lender requirements and applicable limits.
Depending on the buyer's circumstances, one structure may be considerably more useful than the other.
That is why I do not want my Katy, TX buyers deciding where to negotiate $10,000 of seller flexibility until we have their lender run the actual numbers.
First, $10,000 of Negotiated Value Is Not Necessarily $10,000 of Equal Benefit
This is the central idea.
Suppose a home is listed for $400,000 and, based on the property, comparable sales, market exposure and the seller's circumstances, we believe there may be room to negotiate.
For illustration purposes, let's say the seller is willing to give approximately $10,000 somewhere in the transaction.
There are several ways a negotiation could potentially be structured, depending on what the seller agrees to and what the buyer's financing permits.
For example:
- Reduce the purchase price
- Provide an allowable contribution toward buyer closing costs
- Address negotiated repairs
- Provide another permitted concession
- Use some combination of negotiated terms
Those alternatives are not necessarily financially equivalent to the buyer.
And they are not available in unlimited amounts.
The buyer's loan program, lender requirements, appraisal, contract terms and other rules can affect what is permitted.
That is why this needs to be coordinated with the buyer's lender before we structure the offer.
What Happens If You Negotiate $10,000 Off the Purchase Price?
Let's start with the easiest option to understand.
Suppose the seller agrees to reduce a $400,000 purchase price to $390,000.
The buyer is now purchasing the home for $10,000 less.
That can affect the amount being financed and, depending on the loan structure, may reduce the principal-and-interest payment.
But there is an important point buyers sometimes overlook:
A $10,000 reduction in purchase price does not normally reduce the buyer's monthly payment by $10,000 divided over a few months.
For a financed purchase, the benefit of that lower price is generally spread across the financing structure over time.
The exact impact depends on factors including:
- Down payment
- Loan amount
- Interest rate
- Loan term
- Mortgage insurance, if applicable
- The buyer's specific loan program
I am a REALTOR®, not a mortgage lender, so I want the lender calculating the actual financing impact for the buyer.
What Happens If the Seller Contributes $10,000 Toward Allowable Closing Costs?
Now consider a different scenario.
Instead of reducing the price by $10,000, suppose the seller agrees to contribute up to $10,000 toward allowable buyer costs, subject to the contract, loan program, lender approval and applicable limits.
Depending on the transaction and financing, eligible costs can potentially include certain closing costs, prepaid items or other lender-approved expenses.
The specific permitted uses and limits vary.
That distinction matters because a seller contribution can potentially reduce the amount of cash the buyer needs to bring to closing.
For some buyers, preserving several thousand dollars of cash can be more valuable immediately than receiving the same nominal amount as a reduction in purchase price.
For another buyer, the lower purchase price may be the higher priority.
Neither answer is automatically correct.
A Simple Example Shows Why the Difference Matters
Consider two hypothetical transactions involving the same home.
Scenario A: Lower Purchase Price
Original price: $400,000
Negotiated price: $390,000
The buyer receives a $10,000 reduction in the price of the property.
Scenario B: Seller Contribution
Purchase price: $400,000
Seller contribution: up to $10,000 toward allowable buyer costs
In this scenario, the purchase price remains $400,000, but the buyer may be able to reduce certain eligible out-of-pocket costs at closing, subject to financing requirements and other applicable limitations.
Which buyer is better off?
We do not have enough information to answer that question.
And that is precisely the point.
We need the buyer's lender to calculate both scenarios using the buyer's actual loan.
Why Cash to Close Can Matter Just as Much as the Monthly Payment
Many buyers understandably concentrate on the monthly mortgage payment.
But buying a home also requires cash.
Depending on the transaction, that can include:
- Down payment
- Closing costs
- Prepaid expenses
- Initial escrow funding where applicable
- Inspection expenses
- Moving expenses
- Immediate repairs or improvements
- Cash reserves after closing
That last item deserves more attention than it sometimes receives.
I generally do not want a buyer unnecessarily draining every available dollar simply to get through the closing table.
Homes require maintenance.
Moving costs money.
Furniture, appliances, window coverings and other expenses can appear quickly after closing.
If an allowable seller contribution helps a buyer preserve cash while still purchasing a home they can comfortably afford, that may be worth evaluating with the lender.
Could a Seller Contribution Be Used to Reduce the Mortgage Rate?
Potentially, depending on the buyer's financing, lender and loan program.
For example, a lender may be able to explain whether permitted funds can be applied toward discount points or another eligible financing cost.
But I want to be very clear about the division of responsibilities here.
I am not a lender, and I do not advise buyers which mortgage product, interest-rate structure or financing strategy they should select.
My job is to negotiate the real estate transaction.
The lender's job is to explain the financing, including:
- What seller contributions are permitted
- Maximum contribution limits
- Which costs are eligible
- Whether discount points are available or appropriate
- How different structures affect the buyer's payment
- How much cash the buyer would need to close
Then the buyer can make an informed decision.
Do Not Assume a Mortgage Rate Buydown Is Automatically the Best Choice
When mortgage rates are elevated, the phrase "rate buydown" gets a lot of attention.
But buyers should understand what they are being offered.
Different financing arrangements can work differently, and their costs and benefits can vary.
A buyer should ask the lender questions such as:
- Is this a permanent reduction in the interest rate or a temporary structure?
- What does it cost?
- How much does it change the monthly payment?
- How long would it take for the upfront cost to be recovered through payment savings?
- What happens if the buyer sells or refinances before that point?
- Are there other ways the available seller contribution could be used?
I want buyers understanding the financing rather than simply responding to an attractive advertised rate.
The Seller May Care How We Structure the $10,000 Too
This is not only a buyer calculation.
The seller is evaluating the offer from the other side.
A seller may look at:
- Net proceeds
- Purchase price
- Requested seller contributions
- Financing terms
- Repair requests
- Closing date
- Option period
- Other contract terms
That means two offers that appear similar to the buyer may not look identical to the seller.
We have to structure the offer with both sides of the negotiation in mind.
The goal is not simply to ask for the largest concession. The goal is to structure an offer that advances the buyer's priorities while still having a reasonable chance of being accepted.
What If the Seller Will Give $10,000 but the Buyer Cannot Use All of It?
This is another reason the lender needs to be involved before the contract is finalized.
A buyer should not assume that every dollar of a negotiated seller contribution can necessarily be used.
Loan programs can impose limits on seller contributions, and eligible closing costs can vary.
Depending on the transaction, there may also be situations in which the buyer simply does not have enough eligible costs to use the entire amount being discussed.
That can make a poorly structured negotiation less valuable than it initially appears.
I would much rather know that before we write the offer.
Appraisal Still Matters
Suppose a buyer and seller agree to a $400,000 purchase price with a seller contribution rather than reducing the price to $390,000.
That does not mean the property automatically supports a $400,000 value.
If the buyer's financing requires an appraisal, the property still needs to satisfy the lender's applicable appraisal requirements.
A seller concession does not replace the appraisal process.
This can be especially important when buyers compare offers involving different combinations of price and seller-paid costs.
Again, the lender should explain the financing and appraisal implications for the particular transaction.
New Construction Makes This Comparison Even More Important
Katy, TX buyers shopping for new construction frequently encounter builder incentives.
A builder may advertise:
- A promotional mortgage rate
- Closing-cost assistance
- Design-center incentives
- Price reductions
- Financing incentives tied to an affiliated or preferred lender
Those offers can be valuable.
But I do not want a buyer comparing builders based solely on the largest advertised incentive.
We need to understand:
- The actual purchase price
- The financing terms
- Whether using a particular lender is required
- How long an advertised rate applies
- Closing costs
- Property taxes
- Homeowners insurance
- HOA assessments
- MUD taxes or other assessments where applicable
- The buyer's expected total monthly housing cost
A $10,000 incentive is not valuable merely because the number is $10,000.
We need to understand exactly what it does for the buyer.
Property Taxes and Insurance Still Affect the Real Monthly Cost
Even after we decide how to negotiate the purchase, the mortgage principal-and-interest payment is only part of the homeowner's monthly cost.
Property taxes and homeowners insurance can materially affect the total payment.
That is particularly important when comparing homes in different Katy-area communities.
Two homes can have the same purchase price and very different property tax obligations.
New construction can require additional attention because a prior tax bill may reflect primarily the lot or an incomplete improvement rather than the completed home.
If the mortgage is escrowed and future property taxes increase after the completed home is placed on the tax roll, the required escrow portion of the monthly mortgage payment may also increase.
That is why I want buyers evaluating the total cost of ownership, not simply the sales price or advertised mortgage payment.
When Might a Lower Purchase Price Be More Important?
There are circumstances in which a buyer may place greater value on reducing the purchase price.
For example, the buyer may have sufficient cash available and may be more concerned about the amount being paid for the property.
The buyer may also prefer to reduce the amount financed, depending on the loan structure.
Or current comparable sales may suggest that negotiating the price itself should be the priority.
These are transaction-specific decisions.
The important thing is that the buyer understands the tradeoff.
When Might Closing-Cost Assistance Be More Important?
For another buyer, preserving cash may be the larger priority.
Perhaps the buyer has the income to comfortably support the home but would prefer to keep additional reserves after closing.
Perhaps there are moving expenses or improvements planned after the purchase.
Perhaps the lender identifies an eligible use of seller contributions that produces a result the buyer prefers.
Again, the answer depends on the buyer's circumstances and financing.
That is why I do not want to make the decision for the buyer before the lender runs the numbers.
Could We Split the Difference?
Potentially.
Negotiations are not necessarily limited to choosing between exactly $10,000 off the price or exactly $10,000 toward costs.
Depending on the seller, financing and other transaction considerations, the parties could potentially negotiate a combination.
For example, the buyer might prioritize some reduction in price while also requesting an allowable contribution toward certain costs.
Whether that makes sense depends on the property and the transaction.
This is where a coordinated conversation between the buyer, REALTOR® and lender can be particularly useful.
How I Would Approach This With a Katy, TX Buyer
If we believe a seller has approximately $10,000 of negotiating flexibility, I do not want to immediately write:
"Ask for $10,000 off."
Instead, I want to know what the buyer is trying to accomplish.
I would ask:
- Is your biggest concern the monthly payment?
- Is cash to close the bigger issue?
- Do you want to preserve additional reserves?
- Are there repairs that need to be addressed?
- Is reducing the purchase price your highest priority?
Then I want the lender to show the buyer what the financing alternatives actually look like.
After that, we can decide what real estate terms we want to negotiate.
That is a much better strategy than assuming every $10,000 concession has the same value.
Today's Mortgage-Rate Environment Makes This Conversation More Important
This discussion is especially relevant when mortgage rates are elevated.
As I explained in my companion guide, the Federal Reserve influences the broader interest-rate environment but does not directly set the mortgage rate offered to a home buyer.
For buyers, the practical issue is how the current financing environment interacts with the specific home and the negotiating opportunity in front of us.
A higher-rate environment may reduce purchasing power.
But on some properties, buyers may simultaneously have greater negotiating leverage.
That makes it even more important to understand what we are negotiating and why.
The Better Question Is Not "Can We Get $10,000?"
The better question is:
"If we can negotiate $10,000 of value, where does that value help this buyer the most?"
Maybe it is the price.
Maybe it is allowable closing costs.
Maybe the lender identifies another permitted financing use.
Maybe repairs are more important.
Maybe a combination produces the result the buyer prefers.
There is no universal answer.
And that is exactly why good buyer representation involves more than simply negotiating the lowest possible purchase price.
Buying a Home in Katy, TX?
If you are looking at homes in Katy, TX and wondering how to structure an offer in today's market, I can help you evaluate the property, comparable sales, competition and negotiating environment while coordinating with your lender on the financing side.
I am not a lender and do not provide mortgage advice. Your lender should explain your loan program, interest rate, APR, allowable seller contributions, closing costs and financing alternatives.
My role is to help you understand the real estate side of the transaction and negotiate terms based on your priorities.
Call or text me at 281-549-8099 or learn more about working with me at Jonathan.NestAhead.com.
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX and Greater Houston
281-549-8099
Jonathan.NestAhead.com
Local Roots | Global Reach
This article is provided for general real estate education and is not mortgage, lending, financial, tax, legal or investment advice. Seller contributions, eligible closing costs and financing requirements vary by loan program, lender and transaction. Buyers should discuss their individual financing with a qualified mortgage professional.
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way