
Categories
Home Buying TipsPublished September 24, 2026
Should I Wait for Mortgage Rates to Drop Before Buying a Home in Katy, TX?
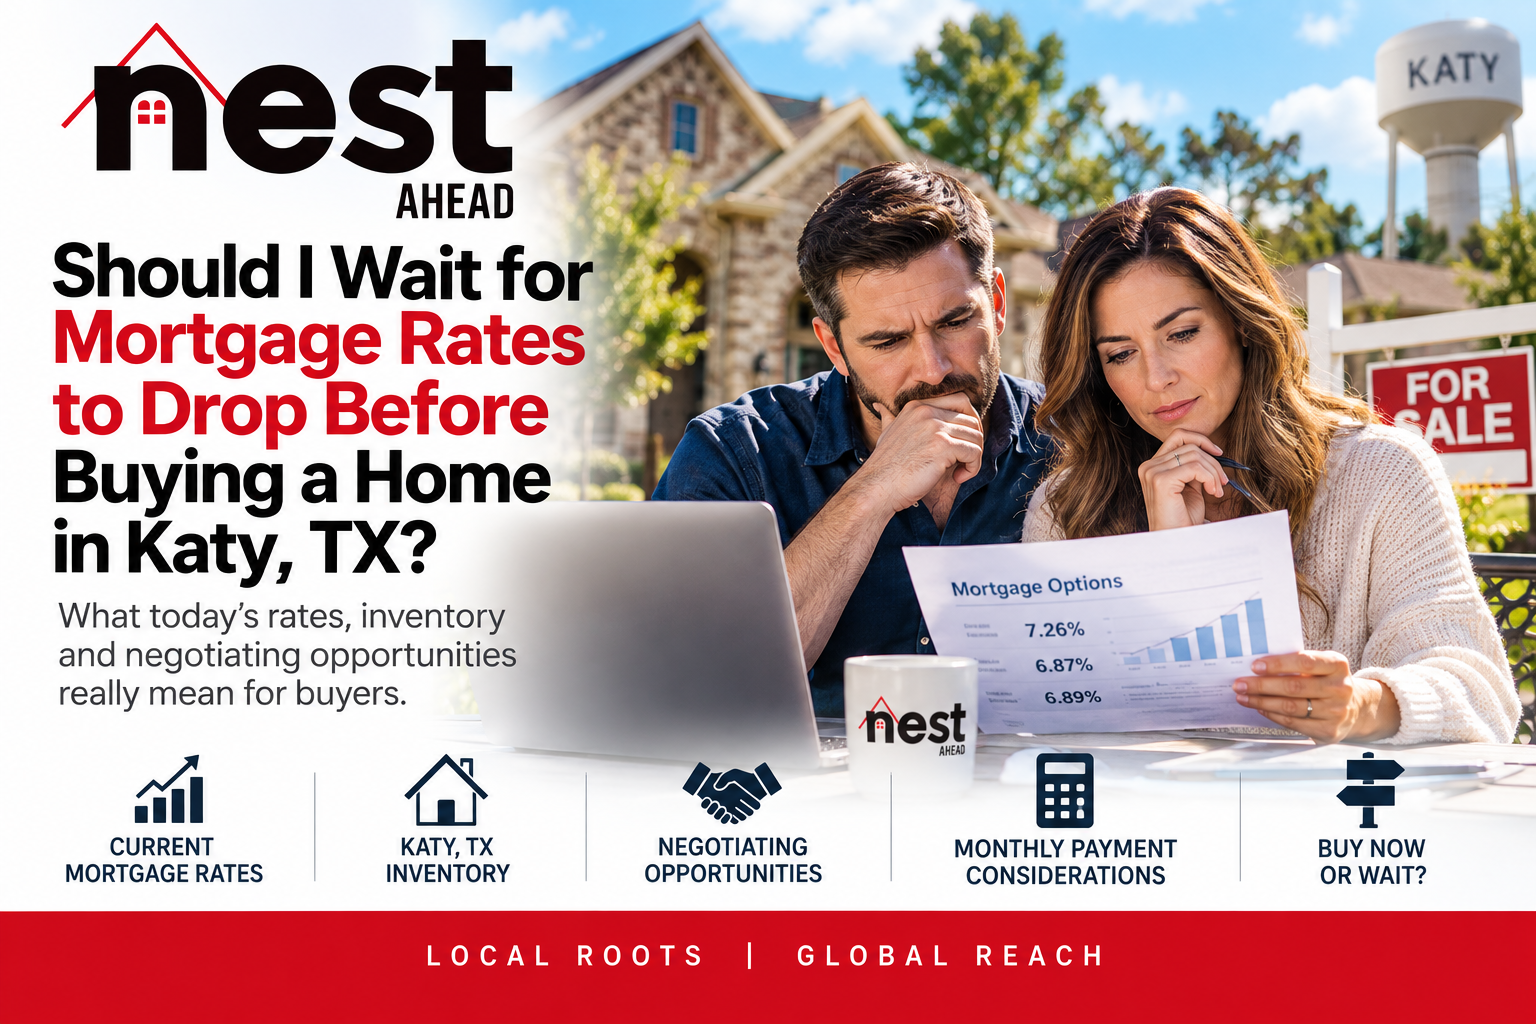
If mortgage rates are above 7%, should you wait for them to come down before buying a home in Katy, TX?
That sounds like a simple question.
It isn't.
Mortgage News Daily reported an average 30-year fixed mortgage rate of 7.26% on September 23, 2026, up 0.09 percentage point from the previous day. Mortgage News Daily described that as matching the highest mortgage-rate level since May 2024.
Mortgage News Daily: Daily Mortgage Rate Index
When buyers see a number like that, a perfectly reasonable thought is:
"Maybe I should just wait until mortgage rates come back down."
Maybe waiting is the right decision for you.
But I would not make that decision based on the assumption that we know where mortgage rates are going next.
We don't.
I also would not tell someone to buy a home today simply because they can "always refinance later."
There is no guarantee that a future refinance will make sense or even be available on the terms a buyer hopes for.
The better question is whether buying a particular home works for you using the financing, payment, market conditions and negotiating opportunities that actually exist today.
What Are Mortgage Rates Right Now?
As of September 23, 2026, Mortgage News Daily reported the following average rates:
- 30-year fixed: 7.26%
- 15-year fixed: 6.87%
- 30-year FHA: 6.87%
- 30-year VA: 6.89%
- 30-year jumbo: 7.40%
These are market averages reported by Mortgage News Daily, not a quote for an individual borrower.
Your actual mortgage rate can depend on the lender, loan program, credit profile, points, loan amount, property, occupancy, lock period and other factors.
I am a REALTOR®, not a mortgage lender, so I do not quote or determine mortgage rates.
If you are considering buying, your lender should show you the actual financing options available to you.
Will Mortgage Rates Go Down?
They might.
They might also rise.
Or they could remain within a relatively narrow range for a period of time.
Anyone making a home-buying decision based on a confident prediction about exactly where mortgage rates will be several months from now is making that decision around something nobody can guarantee.
Mortgage rates respond to a complicated mix of economic data, inflation expectations, bond-market activity, monetary-policy expectations and other factors.
That is why I don't believe a buyer should hear:
"Rates are definitely coming down, so wait."
Or:
"Buy now because rates are definitely going higher."
Neither statement gives the buyer a sound decision-making framework.
If Rates Drop, Won't I Automatically Be Better Off Waiting?
Not necessarily.
A lower mortgage rate could improve affordability if everything else remained exactly the same.
But everything else may not remain the same.
Consider what could change while you wait:
- The price of the home you want
- The number of homes available
- The number of other buyers competing with you
- Seller willingness to negotiate
- Builder incentives
- Your income or employment
- Your credit profile
- Your available cash
- Property taxes and insurance costs
- Your personal housing needs
If mortgage rates fall enough to improve affordability for a meaningful number of buyers, it is possible that more buyers could enter or re-enter the market.
That could affect competition and negotiating conditions.
That is a possibility, not a prediction.
The point is that you cannot evaluate the decision using the mortgage rate alone.
What Is Happening With Housing Inventory in Katy, TX?
This is where the local market matters.
Katy is not one uniform housing market.
According to September 2026 market updates from the Houston Association of REALTORS®, inventory varies considerably among major Katy market areas:
- Katy Southeast: approximately 4.1 months of inventory
- Katy Southwest: approximately 4.9 months of inventory
- Katy North: approximately 5.9 months of inventory
HAR: Katy Southeast Market Update
HAR: Katy Southwest Market Update
Those differences matter.
A buyer looking at one price range in Katy North may encounter a different negotiating environment from someone looking at another price range in Katy Southeast.
Even within the same broad market area, conditions can differ by neighborhood, price range, property type and condition.
This is why a national headline about mortgage rates cannot tell you whether a particular Katy home is a good opportunity.
Do Higher Mortgage Rates Give Buyers More Negotiating Power?
Not automatically.
But higher rates can reduce affordability for some buyers, and increased inventory can create more competition among sellers.
That can sometimes create negotiating opportunities.
Depending on the particular property and seller, a buyer may be able to negotiate around things such as:
- Purchase price
- Seller-paid closing costs
- Contributions that may be used toward eligible financing costs
- Repairs
- Closing date
- Other contract terms
But none of those should be assumed.
A well-priced home in excellent condition may still attract significant buyer interest.
A seller may have little interest in negotiating.
Another property may have been on the market longer and present a completely different situation.
Negotiating leverage is property-specific.
Could a Seller Help Lower My Mortgage Rate?
Potentially.
Depending on the loan program, lender requirements, contract terms and seller's willingness to negotiate, seller contributions may sometimes be used toward eligible buyer closing costs or financing expenses.
That could include discount points associated with a permanent interest-rate buydown or costs associated with an eligible temporary buydown structure.
But this is where the lender needs to be involved.
I do not want to negotiate a seller contribution first and then discover that the buyer cannot use it in the way we intended.
Before deciding whether the buyer should pursue a price reduction, closing-cost contribution or financing-related concession, I want the buyer's lender running the numbers.
Is $10,000 Off the Price Better Than $10,000 Toward Closing Costs?
Not necessarily.
This is one of the most important concepts for buyers to understand in the current market.
Imagine a seller is willing to negotiate approximately $10,000 of economic value.
That $10,000 might potentially be structured in different ways, depending on the transaction:
- A lower purchase price
- Eligible buyer closing costs
- Discount points
- An eligible temporary buydown
- Repairs or other negotiated items
The option that produces the biggest headline discount may not produce the most useful benefit for that particular buyer.
A buyer focused on preserving cash may have different priorities from a buyer focused primarily on reducing the monthly payment.
That is why I want to ask:
"Where does this negotiation create the most usable value for this buyer?"
Then the lender can provide the financing calculations and we can use those numbers when evaluating the real estate negotiation.
Should I Buy Now and Just Refinance Later?
I would not buy a home today based on the assumption that you will refinance later.
A refinance is a new mortgage transaction.
Whether refinancing makes sense in the future can depend on future interest rates, your financial circumstances, the property's value, available loan programs, closing costs and how long you expect to own the home.
Freddie Mac notes that refinancing can involve closing costs and that homeowners should consider whether the expected savings justify those costs.
Freddie Mac: When Is the Right Time to Refinance?
Could rates eventually fall enough that refinancing makes sense?
Yes.
But I want the home purchase to make sense without requiring that future event to occur.
If refinancing later becomes advantageous, great.
It should be a potential future opportunity, not the financial foundation of today's purchase decision.
What if Today's Mortgage Payment Is Higher Than I Want?
Then that matters.
I don't believe the answer is to stretch the budget simply because someone is afraid of missing a house.
You may need to:
- Look at a different price range
- Compare different loan options with your lender
- Increase your down payment if appropriate and feasible
- Evaluate whether seller contributions could help
- Consider a different neighborhood or property type
- Continue saving
- Improve aspects of your financial profile where appropriate
- Wait
Waiting is a perfectly legitimate strategy when buying today does not work for your finances or your life.
The important distinction is between waiting because the numbers do not work and waiting because someone promised you a particular future mortgage rate.
What Should I Ask My Lender Before Deciding?
Before deciding whether to buy or wait, I would want actual financing numbers rather than assumptions from an online mortgage calculator.
Questions for your lender may include:
- What interest rate and APR could I qualify for today?
- What would my estimated principal and interest payment be?
- What are the estimated property taxes and insurance?
- Would mortgage insurance apply?
- What are my estimated closing costs?
- How much cash would I need at closing?
- What would paying discount points accomplish?
- What would an eligible temporary buydown look like?
- How would a seller contribution affect my cash-to-close or payment?
- How would the numbers change at several different purchase prices?
I am not a lender, so those financing calculations need to come from the appropriate mortgage professional.
Once we have them, however, they become extremely useful when evaluating homes and negotiating offers.
What Should I Ask My REALTOR®?
Your lender helps answer:
"What does the financing look like?"
Your REALTOR® should help answer:
"What does the real estate opportunity look like?"
For a particular Katy, TX home, I want to investigate questions such as:
- What have comparable homes actually sold for?
- How long has this home been on the market?
- Has the price changed?
- What competing homes are available?
- What is happening within this particular neighborhood and price range?
- Is nearby new construction competing for the same buyer?
- What incentives are builders offering, if applicable?
- What property condition issues should we consider?
- Are there MUD taxes, HOA assessments or other property-specific costs?
- Where might a negotiation realistically create value?
The answers can be very different from one property to another.
What About New Construction in Katy, TX?
New construction deserves special attention when mortgage rates are elevated.
Some builders may offer financing incentives, closing-cost assistance or other promotions, sometimes conditioned on using an affiliated or preferred lender or title provider.
A large advertised incentive can be attractive.
But buyers should compare the entire transaction.
I want to look at:
- Purchase price
- Interest rate and financing terms
- Points and fees
- Closing costs
- Builder incentives
- Property taxes
- MUD taxes or other assessments where applicable
- HOA assessments
- Insurance
- Included upgrades and features
- Resale alternatives
The lowest advertised mortgage rate does not automatically mean the lowest overall cost or the best home for you.
What About VA Buyers?
If you are eligible for VA financing, your numbers may look different from the conventional 30-year rate you see in a headline.
For example, Mortgage News Daily's September 23, 2026 index showed an average 30-year VA rate of 6.89% compared with 7.26% for its average 30-year fixed rate.
Those are market averages, not individual loan quotes.
If you are considering VA financing, work with an appropriate VA lender to determine your actual eligibility, rate and financing options.
On the real estate side, I have also prepared a guide specifically for buyers looking for an agent familiar with VA-financed transactions:
How Do I Find a Real Estate Agent Experienced With VA Buyers in Katy, TX?
I am a VA Certified REALTOR®, Military Relocation Professional (MRP) and approved Veterans Land Board participating REALTOR®. My role is the real estate side of the transaction while the lender handles eligibility, underwriting and financing.
So, Should I Wait for Mortgage Rates to Drop?
Maybe.
If today's payment does not work for your budget, if your financial situation is not where you want it to be, or if buying does not make sense for your current plans, waiting can absolutely be the right decision.
But I would not wait solely because someone predicts a particular mortgage rate is coming.
And I would not buy solely because someone tells you rates could go higher.
Instead, evaluate what you can actually control:
- Your budget
- Your available cash
- Your financing options
- The homes currently available
- The local market
- The negotiating opportunity
- Your timeline
- Your reasons for moving
Then make the decision using real numbers.
Don't buy because someone tells you mortgage rates are about to fall.
Don't automatically wait because someone tells you today's rates are too high.
Make the decision using the house, market, financing and budget that actually exist today.
Thinking About Buying a Home in Katy, TX?
If you're trying to decide whether buying now makes sense or whether you should wait, we can start without assuming that you need to purchase anything.
We can look at the homes available in the areas you're considering, current local market conditions, recent comparable sales and where negotiating opportunities may exist.
Your lender can then provide the financing numbers you need to evaluate the actual monthly cost.
That gives you something much more useful than trying to predict next month's mortgage rate:
A decision based on your situation and today's real numbers.
Call or text me at 281-549-8099 or learn more about working with me at Jonathan.NestAhead.com.
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX and Greater Houston
281-549-8099
Jonathan.NestAhead.com
Local Roots | Global Reach
Mortgage rates and market conditions referenced in this article are current as of September 23, 2026 and can change. Mortgage News Daily rates are market averages and are not an individual loan quote. This article is provided for general real estate education and is not mortgage, lending, legal, tax or financial advice. I am a REALTOR®, not a mortgage lender. Buyers should obtain financing information specific to their circumstances from an appropriately qualified mortgage professional and verify property-specific information before purchasing.
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way