
Categories
Katy, TX Home Buying, Katy TX Real EstatePublished September 7, 2026
Do You Need 20% Down to Buy a House in Katy, TX?
No. A 20% down payment is not universally required to buy a home in Katy, TX.
That misconception keeps some would-be buyers renting longer than necessary because they assume they need tens of thousands of additional dollars before they can even speak with a lender.
Twenty percent down can make sense for some buyers, but it is only one possible financing structure.
Depending on the borrower and the property, certain conventional programs may allow down payments as low as 3%, FHA-insured financing may allow a minimum required investment as low as 3.5% for qualifying borrowers, and eligible VA buyers may be able to purchase with no down payment in many circumstances.
The correct down payment for you is a financing decision that should be evaluated with a qualified mortgage professional. I am a REALTOR®, not a lender, so my role is to help you understand how your financing affects the real estate transaction and home search.
Where did the 20% rule come from?
Twenty percent is often discussed because it can affect mortgage insurance and the amount borrowed on many conventional loans.
But “20% down avoids certain mortgage-insurance costs in many conventional situations” is very different from saying “you must put 20% down to buy a house.”
Those statements are not the same.
A buyer should compare the total financing picture rather than treating one percentage as a universal rule.
Can a conventional loan require less than 20% down?
Yes, some conventional mortgage programs permit significantly less than 20% down for eligible borrowers.
For example, Fannie Mae HomeReady and Freddie Mac Home Possible advertise down-payment options as low as 3%, subject to eligibility requirements.
That does not mean every buyer qualifies or that a 3% down loan is automatically the best choice. Income restrictions, underwriting requirements, credit, debt-to-income ratios, property type and other factors can apply.
Your lender should determine which conventional programs are actually available to you.
What about FHA financing?
HUD states that FHA-insured purchase financing can allow a down payment as low as 3.5% for qualifying borrowers.
FHA financing also includes mortgage-insurance requirements and other program rules that a lender should explain before you choose it.
You can review general FHA information directly through HUD.
Can a VA buyer purchase with no down payment?
Eligible Veterans, service members and certain surviving spouses may have access to VA-backed purchase financing.
The U.S. Department of Veterans Affairs states that a VA-backed purchase loan can often provide a no-down-payment option when program requirements are met.
Eligibility, entitlement, lender underwriting, appraisal requirements and other conditions still apply, so buyers should work with a lender experienced with VA financing.
You can review the program directly through the U.S. Department of Veterans Affairs.
Does putting less down mean you need no money?
No, and this is where buyers can get surprised.
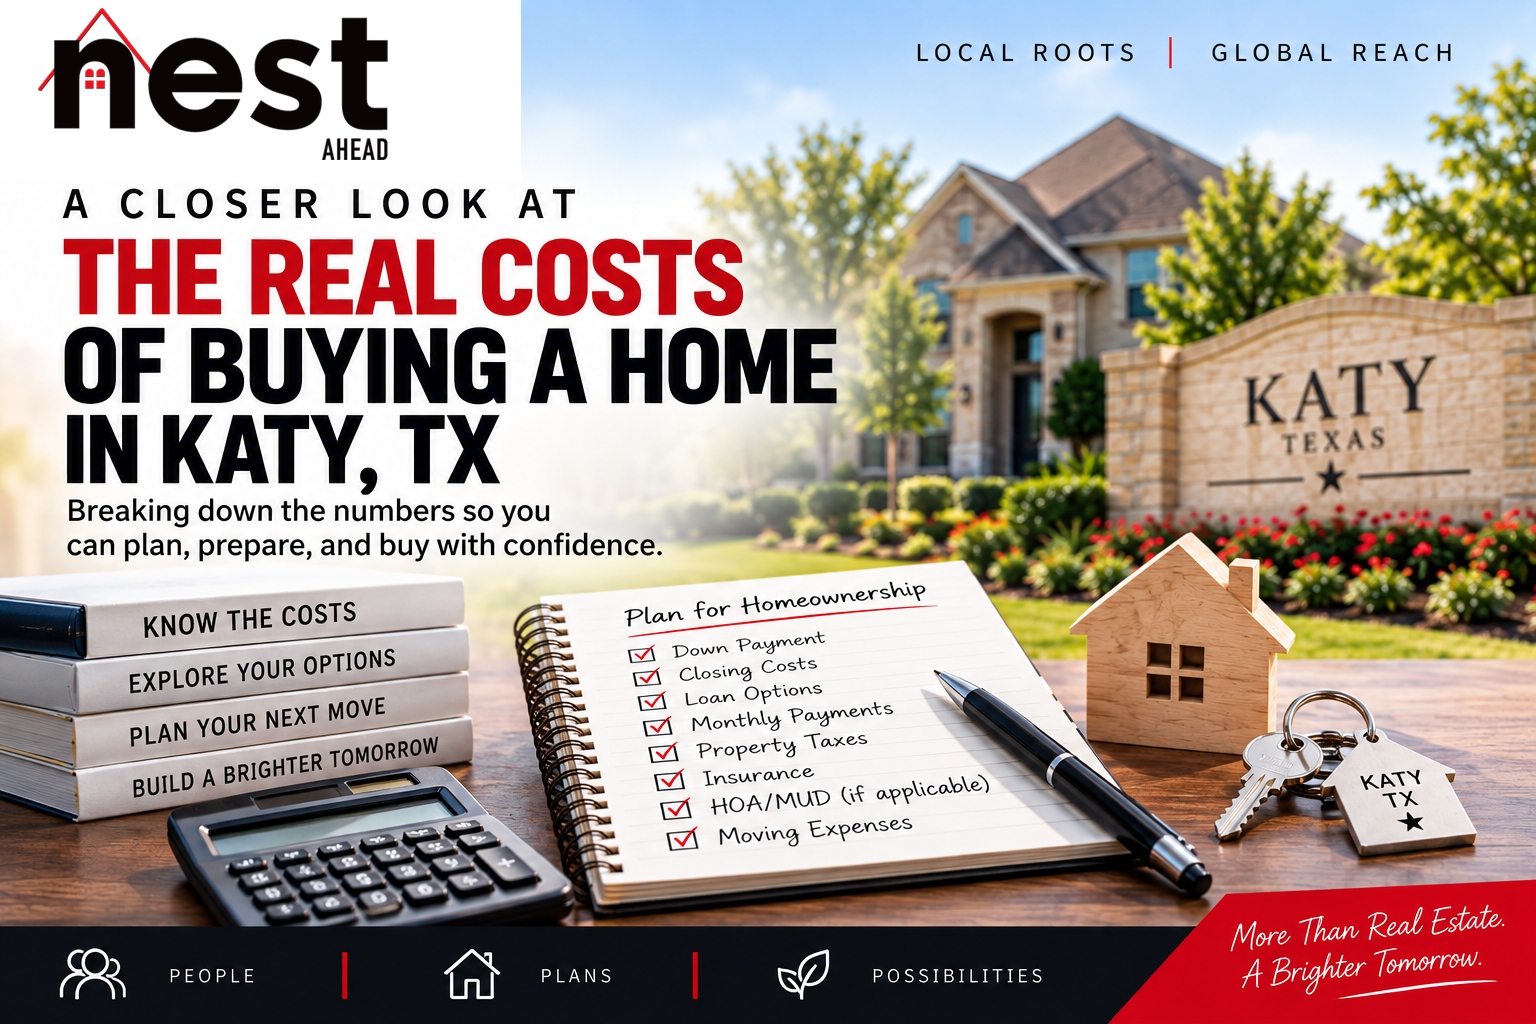
Your down payment is only one part of the money involved in purchasing a home.
- earnest money;
- an option fee;
- home inspections and other due diligence;
- an appraisal when applicable;
- loan and closing costs;
- prepaid insurance and interest;
- initial escrow funding when required;
- moving expenses; and
- cash reserves after closing.
A better question is, “What will my complete cash-to-close and monthly housing cost look like under each financing option?”
Why would someone choose to put 20% down?
There can be legitimate reasons for a buyer to make a larger down payment.
A larger down payment generally means borrowing less money. Depending on the loan, it may also affect mortgage insurance, monthly payment, pricing or other loan terms.
It can also affect how much cash you have left after closing.
Those tradeoffs should be reviewed with your lender and, when appropriate, your financial adviser. A REALTOR® should not tell you how much of your savings you should invest in a down payment.
Is the lowest possible down payment always better?
No.
Just as 20% is not automatically required, the minimum allowable down payment is not automatically the best financial decision.
Putting less down may preserve cash for reserves, repairs or other goals, but it may also increase the amount financed and could affect mortgage insurance or other loan costs.
The right comparison is specific to the borrower.
Can down-payment assistance help?
Some Texas buyers may qualify for programs that provide down-payment or closing-cost assistance.
The Texas Department of Housing and Community Affairs Homebuyer Program provides information about assistance and mortgage options for eligible Texas buyers.
Programs may have income limits, homebuyer-education requirements, approved-lender requirements and other criteria, and funding or program terms can change.
Do not assume you qualify based on a social-media post or an online advertisement. Ask an approved participating lender to verify current eligibility and program terms.
What does this mean when shopping for a Katy, TX home?
Your financing affects more than the down payment.
It can affect your target price, estimated monthly payment, cash reserves, appraisal requirements, closing timeline and how we structure an offer.
Katy-area property taxes can also vary substantially from one property to another, especially where municipal utility districts or other taxing entities are involved.
For that reason, two homes with the same sales price may not have the same estimated monthly housing expense.
You can learn more through my Katy, TX Property Tax Guide and my guide to MUD taxes in Katy, TX.
What should you ask a lender before deciding on a down payment?
Rather than asking only for a preapproval amount, consider asking your lender to compare several scenarios.
- What would my estimated cash-to-close be at different down payments?
- How would the monthly payment change?
- Would mortgage insurance apply, and how would it work?
- What loan programs am I actually eligible for?
- Are there assistance programs I should evaluate?
- How would seller or builder contributions affect the transaction under my loan?
- How much money would I have left in reserves after closing?
Your lender should provide the loan-specific answers.
Once we understand those numbers, I can help you apply them to the real estate search.
The bottom line
You do not automatically need 20% down to buy a house in Katy, TX.
There are financing programs that allow qualified buyers to purchase with substantially less, and some eligible buyers may have access to no-down-payment options.
But “less than 20% down” does not mean “no cash needed,” and the smallest possible down payment is not automatically the best choice.
The best approach is to have a qualified lender calculate your estimated down payment, total cash-to-close and monthly cost under several realistic scenarios.
Then your home search can be built around numbers you actually understand.
For a deeper look at all of the different expenses that may arise during a purchase, read How Much Money Do You Really Need to Buy a House in Katy, TX?.
If you are preparing to buy in Katy, TX, you can also visit my Katy Home Buyer Class for additional buyer education.
Important: Jonathan McNabb is a Texas real estate broker/REALTOR® and is not a mortgage lender, attorney, tax adviser or financial adviser. This article is provided for general real estate education only and is not lending, legal, tax or financial advice. Loan programs, eligibility requirements, interest rates, mortgage-insurance requirements, fees, assistance programs and underwriting guidelines can change and vary by borrower and property. Buyers should verify current terms and eligibility with qualified lending and other appropriate professionals.
About the Author
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX REALTOR® and longtime Katy resident
Local Roots | Global Reach
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way