
Categories
Home Buying TipsPublished September 14, 2026
How Much House Can You Afford in Katy, TX Without Becoming House Poor?
If you are thinking about buying a home in Katy, TX, one of the most important questions is not simply:
“How much house can I qualify for?”
A better question may be:
“How much house can I comfortably afford while still having room in my budget for everything else that matters?”
Those are not necessarily the same number.
A lender can help determine the financing for which you may qualify. But the maximum mortgage amount available to you does not automatically determine what purchase price makes sense for your household.
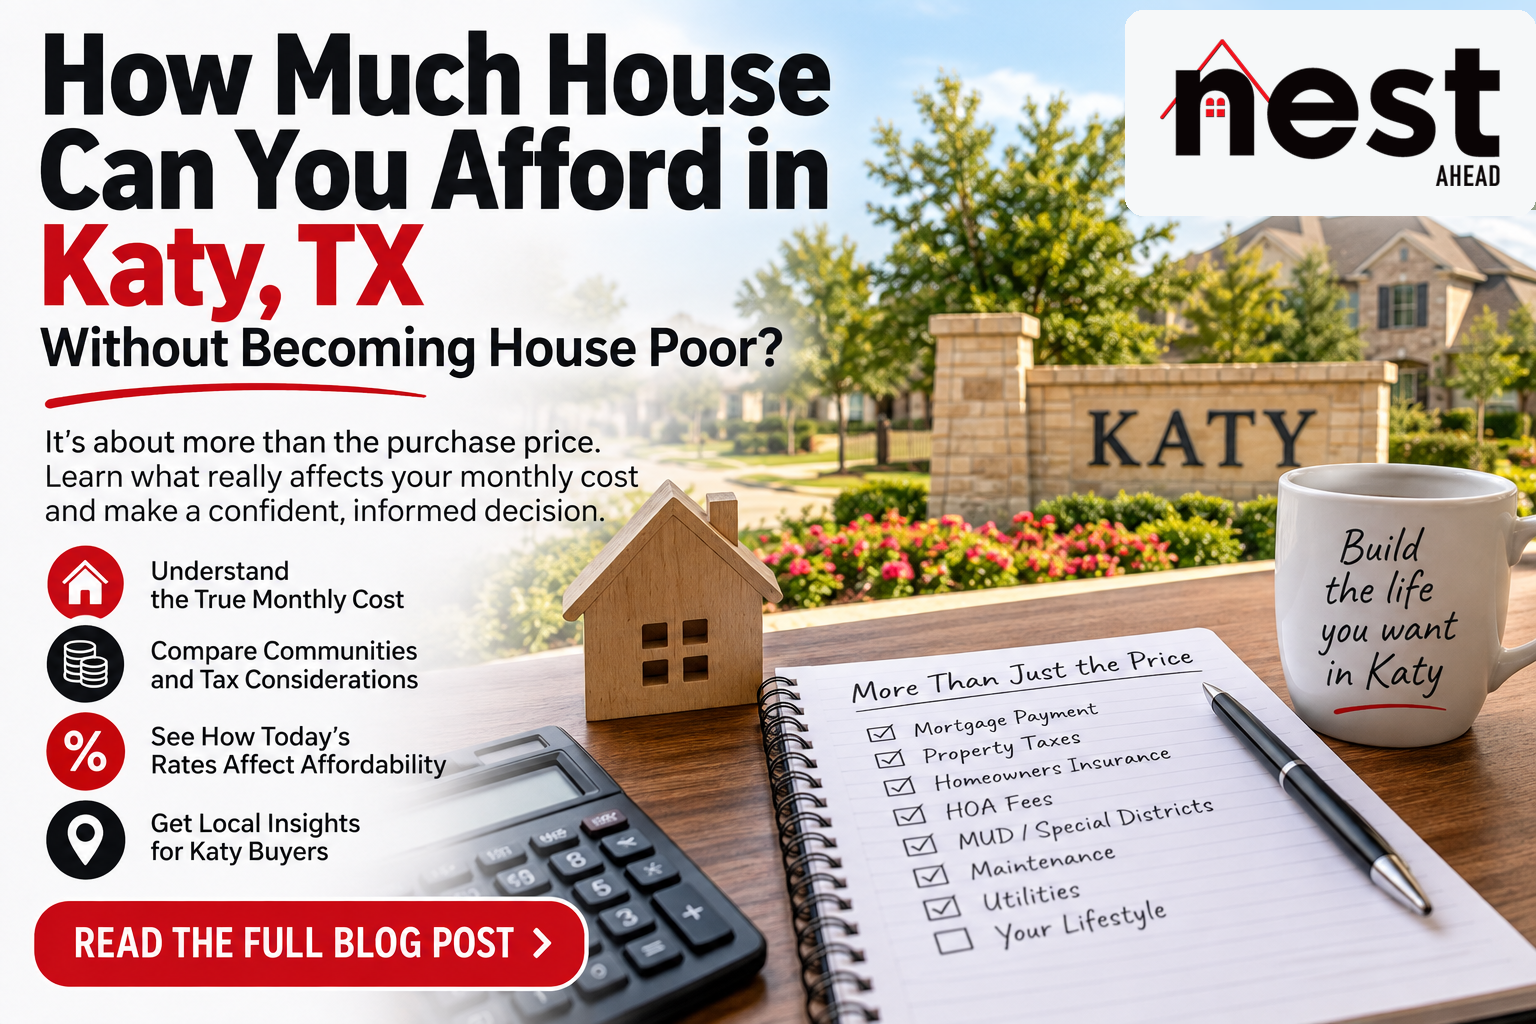
When I work with buyers in Katy, I encourage them to look beyond the sales price and consider the broader ownership picture, including the mortgage payment, property taxes, homeowners insurance, HOA expenses, financing structure and the costs that come with maintaining a home.
That approach becomes especially important around Katy because two homes with similar asking prices can have meaningfully different ownership costs.
Start With the Monthly Cost, Not Just the Home Price
Home buyers naturally focus on sales price. After all, that is the number displayed on the listing.
But a $400,000 home does not automatically create the same monthly cost as every other $400,000 home.
The financing can be different. Property taxes can be different. Insurance costs can be different. HOA assessments can be different. Certain utility or special districts may affect the property's tax burden. Even the condition and age of the home may influence how much you should reasonably expect to spend after closing.
That is why I encourage buyers to compare homes based on the larger financial picture rather than simply assuming that homes at similar prices are financially interchangeable.
Mortgage Qualification and Personal Affordability Are Different Questions
Your mortgage lender is the appropriate professional to evaluate your income, debts, credit profile, loan program and other financial information and determine what financing may be available to you.
My role as your REALTOR® is different.
I can help you understand the real estate surrounding the decision, including the properties you are considering, local market conditions, property-specific costs, contract strategy, comparable housing options and the differences between one home or community and another.
A buyer may qualify for a certain loan amount but decide that purchasing at the very top of that range would leave too little financial flexibility.
Another buyer may intentionally choose a lower purchase price because maintaining savings, traveling, paying for children's activities, investing, reducing other debt or simply having breathing room each month matters more than purchasing the most expensive home possible.
There is nothing wrong with either approach.
The important part is understanding the numbers before making the decision.
What Goes Into the Monthly Cost of Owning a Katy Home?
When comparing properties, buyers should look at more than principal and interest.
Depending on the home and financing, the overall housing-cost picture may include:
- Principal and interest: The portion of the mortgage payment associated with repayment of the loan.
- Property taxes: These vary by property and taxing jurisdiction and can materially affect the monthly amount a homeowner should plan for.
- Homeowners insurance: Premiums vary based on the property, coverage, insurer and other factors.
- Mortgage insurance: Certain financing arrangements may require mortgage insurance.
- HOA assessments: Many Katy-area communities have homeowners associations, and assessments vary considerably.
- Special-district considerations: Some properties are located within MUDs or other special districts whose taxes can be part of the overall property-tax burden.
- Maintenance and repairs: These generally are not part of the mortgage payment, but they remain part of the true cost of homeownership.
- Utilities and recurring property expenses: These may change depending on the size, age, efficiency and features of the home.
Not every cost applies to every buyer or property, and the amounts vary. That is why property-specific research is so important.
Why Two $400,000 Homes in Katy Can Have Different Costs
Imagine two homes that are both offered at approximately $400,000.
At first glance, they may appear equally affordable.
But one could have a different property-tax burden, HOA assessment, insurance profile or maintenance outlook than the other. One buyer could also be using different financing than another.
That means the list price alone does not tell you what owning the property may actually look like from month to month.
This is particularly relevant in the greater Katy area, where communities can fall within different taxing jurisdictions, school districts, utility districts and municipal boundaries.
I discuss that issue in more detail in my guide to Katy mailing addresses, city limits and school districts.
Property Taxes Deserve Special Attention Around Katy
A Katy mailing address does not mean every home is subject to the same taxing entities.
The broader Katy area crosses multiple governmental jurisdictions, and properties that appear relatively close together can have different tax circumstances.
That is why buyers should verify the actual taxing entities and current property information for the individual home rather than relying on a ZIP code, subdivision name or assumption about the area.
When comparing properties, I encourage buyers to look at the property-specific tax information and discuss the estimated payment with their lender.
Also remember that the previous owner's tax bill may not necessarily represent what a new owner ultimately pays. Exemptions, assessed values and other circumstances can change the calculation.
Do Not Forget the Expenses That Are Not Part of the Mortgage Payment
One of the easiest ways to become financially uncomfortable after purchasing a home is to focus entirely on the mortgage payment and forget that homeownership creates other expenses.
A buyer may need to plan for:
- routine maintenance;
- unexpected repairs;
- lawn and landscaping expenses;
- utilities;
- appliance replacement;
- furnishings;
- moving expenses;
- future improvements; and
- an emergency reserve.
This does not mean buyers should be afraid of owning a home.
It means the better affordability conversation considers what happens after closing, not merely whether there is enough money to get through closing.
That is closely related to another question I recently addressed: How much money do you really need to buy a house in Katy, TX?
Do You Need 20% Down Before You Can Afford a Home?
No. A 20% down payment is not a universal requirement for purchasing a home.
Different loan programs have different requirements, and some qualified buyers may have options requiring considerably less than 20% down.
But the smallest available down payment is not automatically the best choice for every buyer either.
A qualified mortgage professional can explain the available financing options and show how different down-payment scenarios may affect the loan, mortgage insurance, cash needed at closing and estimated monthly payment.
For a deeper explanation, see Do You Need 20% Down to Buy a House in Katy, TX?
Today's Mortgage-Rate Environment Makes the Calculation Even More Important
Rate context as of September 11, 2026: Mortgage News Daily's national daily index showed the average top-tier 30-year fixed mortgage rate at 7.12%.
That is a national market index, not a mortgage quote for any individual borrower. Actual rates can vary based on the lender, borrower qualifications, loan type, points and other factors.
You can follow current national mortgage-rate trends directly through Mortgage News Daily.
Why does this matter?
Because changes in mortgage rates can affect the principal-and-interest payment associated with a particular loan amount. A buyer who based a search on an older rate assumption could discover that today's payment looks different even if the home's price has not changed.
That is another reason I prefer buyers to remain in communication with their lender while they are actively shopping rather than relying on numbers calculated weeks or months earlier.
Current Katy Inventory Gives Buyers More to Compare
There is another reason this conversation is timely.
HAR currently classifies both the Katy-Southeast and Katy-Southwest market areas as balanced.
The September 2026 HAR market pages currently show approximately 4.1 months of inventory in Katy-Southeast and 4.9 months in Katy-Southwest.
Those are two distinct HAR market areas and should not be interpreted as a single statistic for all of Katy.
What they do illustrate is something buyers should understand: Katy is not one uniform housing market.
Different parts of the Katy area can have different inventory, pricing, competition and negotiating conditions.
You can review the current market information directly from HAR for Katy-Southeast and Katy-Southwest.
For buyers, a balanced market can create an opportunity to compare options thoughtfully rather than assuming every property will have identical negotiating dynamics.
New Construction Incentives Can Change the Affordability Conversation
Katy-area buyers also have substantial new-construction options, and builder incentives can sometimes affect the affordability calculation.
A builder may offer incentives involving:
- interest-rate buydowns;
- closing-cost contributions;
- design or upgrade credits; or
- other promotional terms.
These offers can be valuable, but buyers should evaluate the entire transaction rather than assuming the largest advertised incentive automatically produces the best financial outcome.
For example, an incentive tied to a builder's preferred lender may need to be compared with alternative financing. Likewise, a rate incentive, price adjustment and closing-cost contribution affect a transaction differently.
Your mortgage professional can help analyze the financing. Your REALTOR® can help you evaluate the real estate and negotiation aspects of the transaction.
If you are weighing a new home against an existing property, my guide to new construction versus resale homes in Katy, TX provides another useful comparison.
Jonathan's Local Insight
One of the mistakes I see buyers make is beginning with a home price instead of the complete picture.
Around Katy, two homes at roughly the same asking price can have different taxes, HOA expenses, insurance considerations, property characteristics and financing scenarios.
That is why I prefer helping buyers compare properties based on what they are actually getting and the costs surrounding each choice instead of assuming two similarly priced homes are financially interchangeable.
I also encourage buyers to establish a relationship with a qualified lender before they become emotionally attached to a particular property.
Knowing your financing options gives us much better information when we begin comparing homes, communities and offer strategies.
How Do You Avoid Becoming House Poor?
There is no universal purchase price or housing-payment percentage that is appropriate for every household.
The more useful approach is to determine what level of housing expense fits your finances and priorities while leaving the amount of flexibility you personally want after purchasing the home.
That means asking questions such as:
- What will my estimated complete monthly housing expense be?
- How much cash will I have left after closing?
- What savings or emergency reserves do I want to maintain?
- What other monthly financial priorities do I have?
- What maintenance could this particular home require?
- How would a different community or property change the tax or HOA picture?
- Would a lower purchase price give me more flexibility?
Those questions can be far more useful than simply asking for the maximum purchase price available under a loan approval.
Frequently Asked Questions About Home Affordability in Katy, TX
How much house can I afford in Katy, TX?
The answer depends on your financing, income, debts, available cash, property taxes, homeowners insurance, HOA expenses and the amount of financial flexibility you want to maintain. A qualified lender can evaluate your financing, while a REALTOR® can help you compare the property-specific real estate factors that affect different homes.
Should I buy the maximum amount my lender approves?
Not necessarily. Loan qualification establishes what financing may be available to you. It does not require you to purchase at the maximum amount. Your personal budget, savings goals, lifestyle and other financial priorities should also be considered.
Do all homes with a Katy, TX address have similar property taxes?
No. A Katy mailing address does not establish identical taxing jurisdictions. Buyers should verify the applicable taxing entities and property-specific information for each home they are considering.
Does a larger down payment always make more sense?
Not necessarily. Different down-payment amounts can affect cash needed at closing, mortgage insurance and the monthly payment. A qualified mortgage professional can help compare financing scenarios based on your circumstances.
Can builder incentives make a new-construction home more affordable?
They can affect the overall transaction, but the details matter. Interest-rate incentives, closing-cost contributions, upgrades and pricing incentives work differently and may carry conditions. Buyers should compare the entire transaction rather than evaluating only the advertised incentive.
Should I speak with a REALTOR® or a lender first?
Both can be helpful early in the process, but they perform different roles. A lender can evaluate financing and qualification. A REALTOR® can help you understand the housing market, properties, transaction and real estate considerations. Ideally, buyers establish both relationships before becoming serious about a particular home.
Thinking About Buying a Home in Katy, TX?
If you are trying to determine what price range makes sense, I can help you compare the real estate side of the equation, including neighborhoods, taxes, HOA considerations, new construction versus resale, local market conditions and the differences between individual properties.
Then your lender can help you evaluate the financing associated with those options.
The goal is not simply to buy the most house possible.
It is to make a home-buying decision that works for you both on closing day and after you move in.
About the Author
Jonathan McNabb, REALTOR®
Broker/Owner | Nest Ahead
Katy, TX
Jonathan McNabb is a Houston native, longtime Katy resident and Broker/Owner of Nest Ahead. He has nearly 30 years of combined experience in the real estate and legal industries and helps buyers, sellers and relocation clients throughout Katy and the Greater Houston area. His educational resources are designed to help consumers understand local real estate decisions using practical, property-specific information and current market context.
Local Roots | Global Reach
281.549.8099
NestAhead.com
This article is for general educational purposes and is not mortgage, financial, tax or legal advice. Mortgage qualification and financing should be discussed with a qualified mortgage professional. Property taxes, insurance, HOA assessments and other costs should be verified for the individual property.
Jonathan McNabb
Broker/Owner | Nest Ahead
or another way